Automotive Supplier R&D Tax Credit Ohio Guide

Automotive suppliers in Ohio frequently perform engineering, testing, tooling, and manufacturing process work that may support an R&D Tax Credit review. The
automotive supplier R&D tax credit Ohio opportunity depends on the technical activity performed, the uncertainty involved, the experimentation used to resolve it, and the documentation connecting the work to qualified expenses.
Quick answer: Automotive suppliers may qualify when they develop or improve components, tooling, production methods, materials, software, or EV systems through documented technical experimentation. Routine production, standard inspections, and customer acceptance procedures generally need to be separated from qualified research.
Since 2004, RCG has completed more than 25,000 R&D tax credit studies and identified over $750 million in tax savings. RCG’s team includes CPAs, tax specialists, engineers, technical writers, and architects who support federal and state R&D Tax Credit studies with audit-ready documentation.
RCG provides R&D Tax Credit support for automotive suppliers across Ohio, including companies in Marysville, East Liberty, Anna, Toledo, Findlay, Dayton, Cleveland, and surrounding automotive manufacturing communities.
Cost Segregation may apply to many property types, including warehouses, manufacturing facilities, medical offices, dental offices, office buildings, industrial properties, retail spaces, and mixed-use commercial properties.
What Automotive Supplier Activities May Qualify?
Automotive suppliers may need an R&D review when projects involve technical uncertainty related to performance, manufacturability, tolerances, materials, durability, safety, quality, or production repeatability.
| Automotive activity | Why it may need R&D review |
|---|---|
| Component development | May involve testing designs, materials, fit, function, or performance. |
| Tooling and fixture design | May involve improving tolerances, repeatability, cycle time, or assembly. |
| Lightweight material testing | May evaluate strength, weight, durability, forming, or compatibility. |
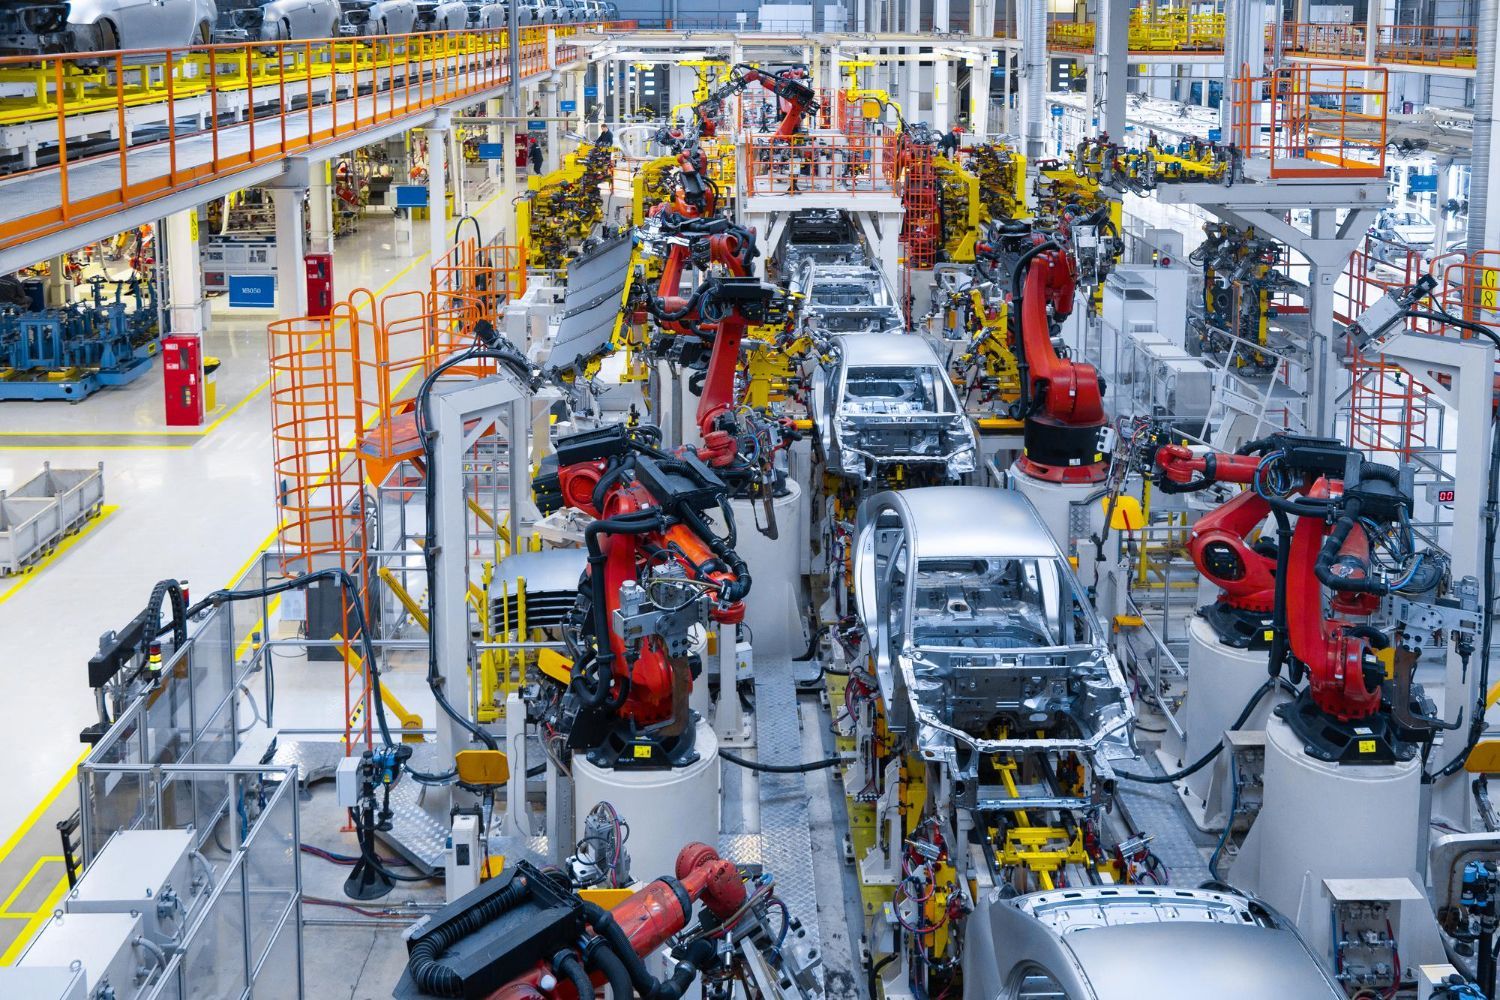
| Production-line improvements | May involve testing equipment layouts, controls, automation, or process settings. |
| EV component development | May involve thermal management, enclosures, connectors, controls, or system integration. |
These activities do not automatically qualify. The supplier should be able to explain the technical objective, alternatives evaluated, tests performed, and results used to guide the project.
How PPAP-Related Testing Should Be Reviewed
Production Part Approval Process activity can include both potentially qualified and routine work. Testing performed to resolve uncertainty about a new component, material, tooling method, or manufacturing process may need review.
However, routine validation, standard documentation, customer submission requirements, or testing performed after technical uncertainty has been resolved may not receive the same treatment. The analysis should identify whether the work involved experimentation or simply confirmed that an established product and process met required specifications.
This distinction helps prevent a supplier from treating all PPAP-related time and costs as qualified research.
Automotive Tooling and Process Improvements
Automotive suppliers often develop custom dies, molds, fixtures, gauges, assembly methods, welding processes, machining strategies, or automated production systems. A
supplier engineering tax credit review may be appropriate when engineers test alternatives to solve technical problems involving dimensional accuracy, material behavior, throughput, defects, or repeatability.
For example, modifying tooling to address springback, testing weld sequences to reduce distortion, or refining machine settings to improve part consistency may require technical experimentation. Routine maintenance, repeat production, and standard setup work generally need to be separated.
EV Component R&D Credit Considerations
Automotive suppliers working on electric vehicle systems may face technical uncertainty involving battery enclosures, connectors, thermal systems, lightweight materials, power electronics housings, sensors, controls, or assembly processes.
An EV component R&D credit review should focus on the work performed, not the fact that the project involves an electric vehicle. Eligibility depends on whether the supplier attempted to develop or improve a business component through documented experimentation.
Documentation for Automotive Supplier Claims
Useful records may include engineering notes, CAD revisions, tooling drawings, test reports, production trial records, material specifications, quality data, process logs, prototype records, project timelines, employee time records, and technical meeting notes.
The documentation should connect employees and expenses to specific projects. It should also separate qualified technical work from routine production, customer communication, maintenance, purchasing, training, and administrative activity.
FAQs About Automotive Supplier R&D Tax Credits
Can Ohio automotive suppliers claim the R&D Tax Credit?
Ohio automotive suppliers may qualify when they perform documented technical work involving component development, tooling, materials, software, testing, or manufacturing process improvements. Eligibility depends on project facts and qualified expenses.
Does PPAP testing qualify for the R&D Tax Credit?
Some PPAP-related testing may need review when it is used to resolve technical uncertainty. Routine approval procedures or validation performed after uncertainty has been resolved generally need to be separated.
Can tooling development qualify?
Tooling development may qualify when engineers evaluate alternatives involving tolerance, durability, material flow, repeatability, cycle time, or manufacturability through documented experimentation.
Do production-line changes qualify?
Production-line changes may need review when they involve technical uncertainty and testing related to automation, controls, equipment integration, throughput, quality, or repeatability. Routine installation alone generally does not qualify.
What records support an automotive R&D claim?
Helpful records include CAD revisions, tooling drawings, test data, production trials, material specifications, engineering notes, project timelines, quality reports, and employee time support.
Review Your Ohio Automotive R&D Activity
The automotive supplier R&D tax credit Ohio opportunity may apply to suppliers developing components, tooling, materials, EV systems, or improved manufacturing processes. Qualification requires project-specific analysis and supportable documentation.
RCG Tax Partners provides technical analysis and audit-ready support for federal and state R&D Tax Credit studies.
RECENT BLOGS

SHARE THIS