Manufacturing Facility Cost Segregation Ohio Guide


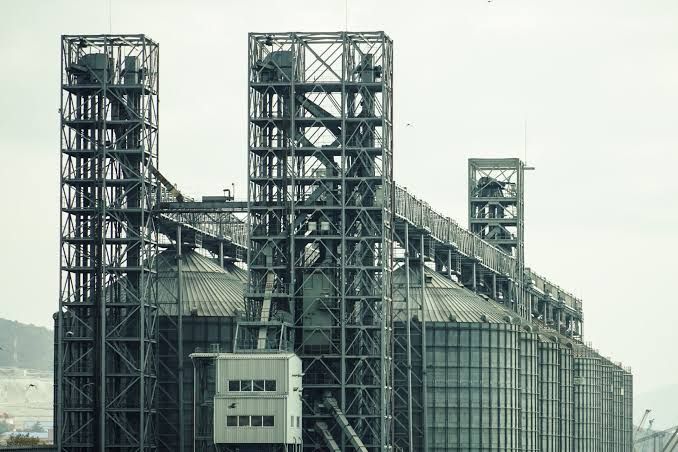
Manufacturing facilities often contain specialized property components that require more detailed depreciation analysis than a standard commercial building. A manufacturing facility cost segregation Ohio study may identify eligible assets and improvements that can be classified into shorter recovery periods based on their function, construction, and relationship to plant operations.

Quick answer: Manufacturing facilities may benefit from Cost Segregation when they include specialized electrical distribution, equipment foundations, process-related utilities, production-area improvements, loading systems, paving, fencing, or other property components. Eligibility depends on the facility facts, asset functions, documentation, and engineering-based analysis.

RCG provides Cost Segregation support for manufacturers across Ohio. Its team includes CPAs, tax specialists, engineers, technical writers, and architects who prepare detailed, audit-ready studies. RCG serves manufacturing businesses in areas such as Cleveland, Akron, Canton, Youngstown, Toledo, Dayton, Lima, Findlay, and surrounding industrial communities.

What Is Manufacturing Facility Cost Segregation?

Cost Segregation analyzes the individual components of a commercial property rather than treating the entire facility as one building asset. Certain components may qualify for shorter depreciation periods when their construction, purpose, and use support a different classification.

For manufacturers, the review may involve a recently purchased plant, new construction, a facility expansion, a production-area renovation, or substantial improvements to an existing building.

A study does not automatically reclassify every specialized feature. Each asset must be evaluated based on its facts and applicable depreciation rules.

Cost Segregation may apply to many property types, including warehouses, manufacturing facilities, medical offices, dental offices, office buildings, industrial properties, retail spaces, and mixed-use commercial properties.

What Manufacturing Property Components May Need Review?

Manufacturing plants often include systems and improvements designed around specific production requirements.

Facility component Why it may need Cost Segregation review
Specialized electrical systems May support particular machinery, production lines, or operational equipment.
Equipment foundations May be designed for specific machines, vibration control, alignment, or load requirements.
Process-related utilities May include compressed air, water, gas, ventilation, or piping serving production functions.
Loading and material-handling areas May include dock components, doors, paving, or operational improvements.
Land improvements May include parking areas, fencing, drainage, sidewalks, or exterior lighting.
Production-area buildouts May include partitions, finishes, or systems tied to manufacturing use.

The asset’s function matters. General building systems may receive different treatment from components installed primarily to support machinery or production operations.

When Should a Factory Cost Segregation Study Be Considered?

A factory cost segregation study may be worth reviewing after:

  • Purchasing an existing manufacturing property
  • Constructing a new plant
  • Expanding production or warehouse space
  • Renovating a facility
  • Adding production lines or technical areas
  • Completing major site or utility improvements


A prior property project may also need review when sufficient records remain available. The appropriate timing and tax treatment depend on the property, placed-in-service dates, existing depreciation records, and the company’s tax position.

Why Engineering-Based Analysis Matters

A general fixed-asset schedule may not explain why a component was installed or how it supports manufacturing operations. Engineering-based analysis examines construction documents, invoices, drawings, asset descriptions, and physical property details to understand each component’s function.

For example, an electrical system serving the entire building may require different treatment from electrical distribution installed specifically for production machinery. A structural slab may differ from a foundation engineered for a particular piece of equipment.

This functional analysis helps distinguish supportable property classifications from broad assumptions.

Documentation for Industrial Cost Segregation in Ohio

Useful documentation may include:

  • Construction drawings and specifications
  • Contractor invoices and payment records
  • Purchase and closing documents
  • Fixed-asset and depreciation schedules
  • Renovation and expansion records
  • Equipment and utility layouts
  • Change orders and project cost details
  • Site plans and property photographs

Records should identify costs clearly enough to connect them to specific building components, systems, or improvements. When detailed invoices are unavailable, other construction and property records may help support the analysis.

How Cost Segregation Differs From the R&D Tax Credit

Manufacturers may qualify for both Cost Segregation and the R&D Tax Credit, but the two strategies address different activities.

Cost Segregation reviews property components and depreciation timing. The R&D Tax Credit reviews qualified technical work such as product development, process improvement, tooling, testing, automation, or manufacturing experimentation.

A plant expansion may create a Cost Segregation review opportunity, while separate engineering work performed within that facility may need R&D Tax Credit analysis. Each study requires its own documentation and eligibility review.

FAQs About Manufacturing Facility Cost Segregation

  • Can an Ohio manufacturing plant qualify for Cost Segregation?

    A manufacturing plant may qualify when its property components, construction costs, improvements, and asset functions support reclassification. Eligibility depends on engineering analysis and documentation.

  • Does Cost Segregation apply to existing factories?

    Yes. Purchased, renovated, expanded, or previously constructed factories may need review. The opportunity depends on available records, depreciation history, and applicable tax requirements.

  • Can equipment foundations be included?

    Equipment foundations may need review when they are designed for specific machinery or production functions. Their treatment depends on construction details, purpose, and supporting records.

  • Are parking lots and exterior improvements reviewed?

    Parking areas, fencing, drainage, sidewalks, landscaping, and exterior lighting may be included in a property review. Classification depends on the nature and function of each improvement.

  • Is Cost Segregation the same as accelerated depreciation?

    Cost Segregation identifies and classifies property components. Those classifications may allow certain assets to be depreciated over shorter recovery periods, affecting the timing of deductions.

Review Your Ohio Manufacturing Property

A manufacturing facility cost segregation Ohio study may help plant owners identify supportable depreciation classifications for specialized systems, production improvements, equipment foundations, and land improvements.

RCG Tax Partners provides engineering-based Cost Segregation studies with detailed documentation for manufacturing properties across Ohio.

RECENT BLOGS

By RCG Tax Partners • September 11, 2026
Learn how 100% bonus depreciation and cost segregation may affect Ohio commercial property owners in 2026. See what property may qualify.
By RCG Tax Partners • September 8, 2026
Learn how cost segregation may apply after buying an existing commercial property in Ohio, including basis allocation and depreciation review.
By RCG Tax Partners • September 4, 2026
Learn which Ohio building projects may still qualify for Section 179D after June 30, 2026 and what construction-start timing means.
By RCG Tax Partners • September 2, 2026
Learn what Form 6765 Section G requires in 2026 for Ohio R&D credit claimants, including business-component reporting and key exceptions.
By RCG Tax Partners • September 1, 2026
Learn when look-back cost segregation in Ohio may use Form 3115 and a Section 481(a) adjustment to address missed depreciation.
By RCG Tax Partners • August 21, 2026
Medical device companies often perform technical work that may support an R&D Tax Credit review. The medical device R&D tax credit Ohio opportunity may apply when a company develops or improves devices, components, firmware, materials, manufacturing processes, or testing methods through documented technical experimentation. Quick answer: Medical device companies may qualify when teams evaluate technical alternatives related to device function, performance, reliability, quality, manufacturability, materials, software, or production methods. Eligibility depends on project-specific facts, qualified expenses, and documentation. Routine quality control, regulatory administration, and testing performed after technical uncertainty has been resolved generally need to be separated. Since 2004, RCG has completed more than 25,000 R&D tax credit studies and identified over $750 million in tax savings. RCG’s team includes CPAs, tax specialists, engineers, technical writers, and architects who support federal and state R&D Tax Credit studies with audit-ready documentation. RCG provides R&D Tax Credit support for medical device and medtech companies across Ohio, including businesses in Cleveland, Beachwood, Columbus, Dublin, Cincinnati, Blue Ash, Dayton, and surrounding healthcare technology and manufacturing communities.

SHARE THIS